For nearly a decade, corporate success was closely tied to rapid expansion, hiring, market growth, and investor confidence. However, as the operating environment grows increasingly expensive and complex, firms are placing a much higher priority on making sound financial decisions.
This shift is particularly prominent in the financial services and banking sector, where digital adoption has generated vast reserves of financial data. Artificial intelligence is now providing institutions with new avenues to leverage this information to automate workflows, personalize services, enhance lending choices, and build stronger financial intelligence.
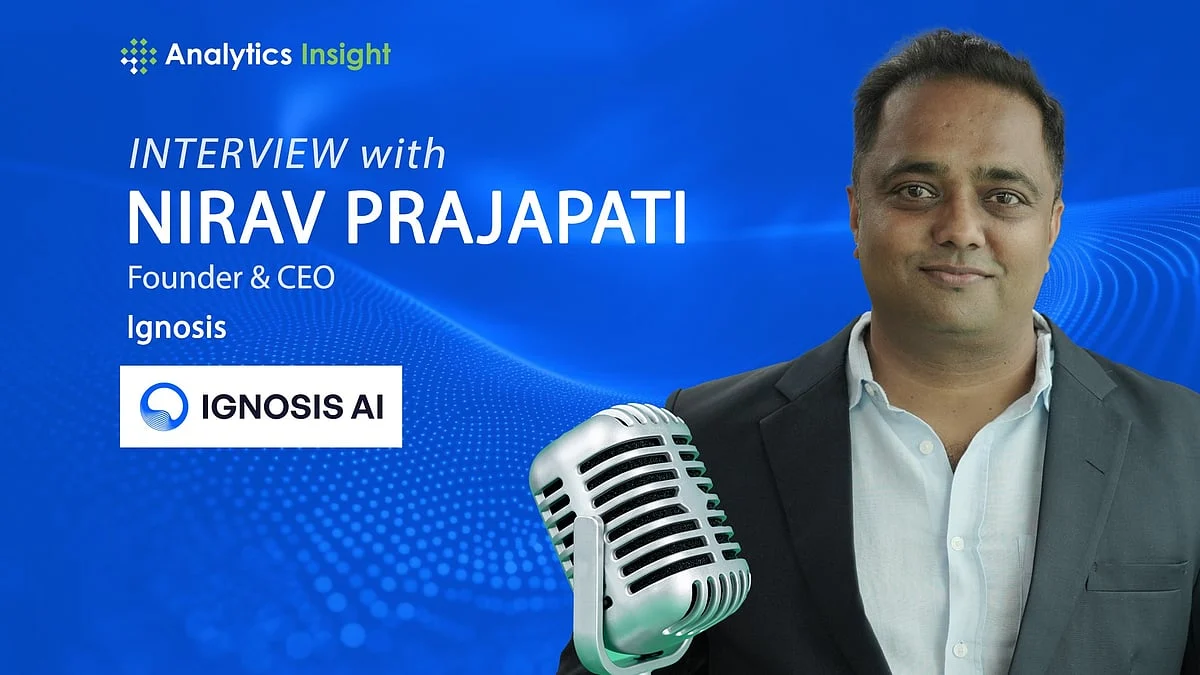
During a recent episode of the Analytics Insight Podcast, Priya Dayalani sat down with Ignosis Founder and CEO Nirav Prajapati to discuss how digital infrastructure, financial data, and AI are transforming the future of banking and financial services. Their conversation also touched upon consent-driven data sharing, India’s digital public infrastructure, and the key investments banks must make to evolve into truly intelligence-driven organizations.
Below are excerpts from the interview:
From Digital Banking to Intelligent Banking: What Has Changed?
While digital banking has already revolutionized how users access financial services and complete transactions, Nirav Prajapati notes that the next evolution centers on harnessing the massive digital footprint generated by these activities to offer tailored financial services.
The expansion of e-commerce, banking applications, UPI, and other digital touchpoints has produced immense quantities of financial data. Utilizing generative AI alongside newer AI models, financial institutions can tap into this data—with explicit customer consent—to deliver highly customized recommendations.
These suggestions may involve loans, credit cards, insurance, investments, or alternative financial goods. Furthermore, AI assistants can help users simplify their finances, monitor spending, and make better financial decisions.
Consequently, the industry is transitioning from basic digital access toward utilizing data and intelligence to craft personalized financial experiences.
How Can AI Make Lending Faster and More Inclusive?
Historically, lending relied heavily on historical repayment patterns and credit bureau reports. Today, however, account aggregator-based consented data sharing allows lenders to tap into a wider array of financial data.
This capability helps institutions evaluate cash flows, operating expenses, business revenue, and other financial behaviors. It also offers small businesses, gig workers, and individuals who are new to credit an easier way to share their banking records.
According to Prajapati, superior lending outcomes hinge on gathering accurate data from reliable sources and interpreting it properly. Financial obligations, income, credit history, and identity insights can then be pooled together to bolster the underwriting decision.
While AI and automation can manage a growing share of these tasks, human oversight remains vital for handling complex scenarios.
Where Will AI Create the Most Immediate Value in Banking?
Voice AI stands out as one of the most immediate use cases highlighted by Prajapati. Banks and financial institutions routinely field massive volumes of calls regarding customer support, product inquiries, payment collections, and financial journeys.
Voice AI can efficiently manage these dialogues at scale, whether by reminding clients about overdue payments or explaining specific products.
Workflow automation represents another critical domain. For instance, during the lending pipeline, AI can assist by gathering documents, extracting data, checking details, verifying them against internal policies, and routing relevant information directly into credit underwriting systems.
Additionally, AI plays a key role in fraud detection, employing models that scan massive datasets to spot patterns linked to potentially fraudulent behavior.
Collectively, these implementations illustrate how AI is already branching out across compliance, lending, voice communication, fraud prevention, and other core banking operations.
How is Account Aggregator Changing Financial Data Sharing?
The account aggregator framework introduces an innovative model for how consumers share financial details with businesses.
In the past, customers frequently had to print, download, or manually deliver bank statements to prospective lenders. Account aggregators enable users to securely share their financial information digitally by granting explicit consent.
Prajapati noted that consumers retain full visibility into who is receiving their data and the specific purpose behind the request. They also hold the right to revoke permission whenever they choose to stop sharing.
This framework empowers users with greater command over their financial records while enabling institutions to retrieve information more seamlessly for processes like lending.
How does India’s Digital Public Infrastructure Support Intelligent Finance?
India’s digital ecosystem is rapidly establishing a robust foundation for the next phase of financial services.
Prajapati highlighted population-scale digital public infrastructure such as UPI, Aadhaar, ONDC, and the Account Aggregator framework. Although India may not have constructed the planet’s largest AI models, he contends that the nation has successfully built digital infrastructure capable of driving large-scale, data-backed services.
This established digital framework serves as a vital bedrock for future AI adoption and tailored financial offerings.
What Should Banks Invest in to Become Intelligence-Driven?
For financial institutions aiming to scale up their AI capabilities, Prajapati pointed to three essential pillars: talent, data, and governance.
The first requirement is a robust data architecture. Banks must organize, clean, and structure enterprise data because the precision of foundational data directly dictates how well AI models perform.
The second pillar focuses on talent. Because AI tools are increasingly embedded across engineering, sales, product development, and other departments, upskilling employees enhances overall productivity and prepares teams to collaborate with these technologies.
The third focus area involves governance and compliance. Automated platforms can flag standard compliance issues, freeing human reviewers to concentrate on higher-risk situations.
When combined, these investments help institutions evolve past basic digital operations and transition toward intelligence-guided decision-making.
What Will Separate Financial Leaders from Those That Fall Behind?
Looking ahead, Prajapati suggests that the top financial institutions will not necessarily be the ones boasting the largest employee bases or the most extensive branch networks.
Instead, competitive advantage will be dictated by how skillfully an organization deploys AI agents, refines feedback loops, automates workflows, adjusts pricing strategies, and speeds up decisions.
For example, continuous underwriting can enable policies and choices to adapt based on ongoing feedback. Simultaneously, organizations must identify where human expertise is indispensable and put appropriate guardrails in place to keep AI functioning as intended.
Ultimately, Prajapati asserts that the competitive edge over the coming decade will belong to those capable of adapting to AI swiftly, acting decisively, and constructing strong feedback loops.
Listen to the full discussion on the Analytics Insight Podcast.