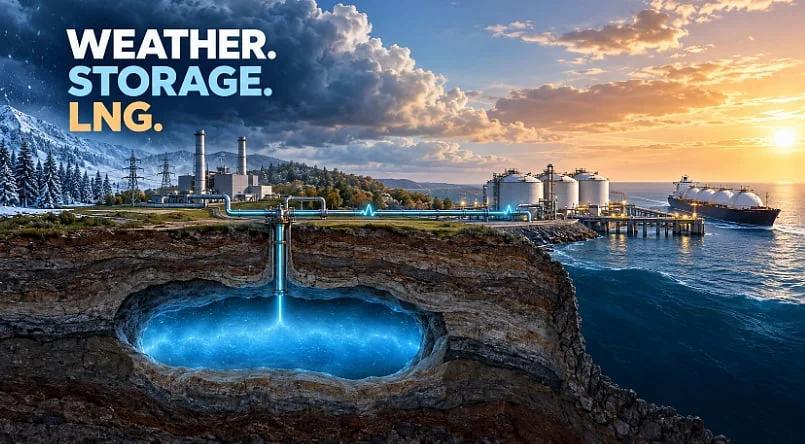
A natural gas price prediction can shift before a single cubic foot of the commodity actually moves. Overnight, a colder weather model emerges, traders begin pricing in a larger storage withdrawal, and an export facility continues pulling heavily from the pipeline grid. By the opening bell, the market has already factored in a tighter supply-demand balance that does not yet exist in the physical data.
Weather Rewrites Demand in a Hurry
Cold weather increases the volume of buildings heated globally. Conversely, elevated temperatures matter just as much because air conditioners draw power from the electrical grid, forcing gas-fired generators to ramp up production. Furthermore, the US Energy Information Administration notes that heavy summer gas consumption can lead to reduced injections into reserves, ultimately leaving less fuel on hand for winter needs.
The market does not wait for actual temperatures to materialize. Traders continuously monitor successive weather-model runs, weighing projected heating and cooling demand across major population hubs. If a model shifts a cold front eastward toward densely populated areas, prices can react even when the national average temperature remains virtually unchanged.
Location often carries more weight than the nationwide average. Severe cold near a specific pipeline bottleneck can spark a localized shortage while other regions stay well-supplied. Although gas may be sitting in storage facilities hundreds of miles away, limited transport capacity can block it from reaching the stressed market in time.
Weather can also disrupt supply. Freezing conditions frequently interrupt wells and processing equipment, while hurricanes can impair offshore production, shipping, or export terminals. The most dramatic price spikes typically happen when severe weather simultaneously drives up consumption and constrains deliveries.
Storage Is the Market’s Safety Cushion
While production remains relatively steady throughout the year, demand experiences seasonal fluctuations. During slower periods, lower demand allows excess gas to be funneled into storage for future use; when demand climbs due to heating needs or power sector requirements, that gas is withdrawn.
However, this buffer has distinct limits. Storage capacity dictates how much gas a facility can hold, while deliverability determines how quickly that gas can be extracted. A massive inventory provides little comfort if operators cannot deliver the fuel to customers quickly enough. Regional positioning, pipeline connectivity, and the specific type of storage facility all dictate this retrieval speed.
The Surprise Moves the Market
Weekly storage figures are always evaluated against market expectations rather than viewed in isolation. A withdrawal of 100 billion cubic feet may sound significant, but if traders anticipated a draw of 115 billion, the outcome is looser than feared, potentially sending prices down. Conversely, a seemingly modest inventory withdrawal can drive prices upward if the market had anticipated an injection.
Comparisons to seasonal norms are equally critical. Inventories sitting above the five-year average give the system enough padding to handle unexpected demand shocks, whereas stocks hovering near the bottom of that range leave little room for error if faced with a colder forecast, production shut-ins, or surging exports. This is why any credible natural gas price prediction must outline the specific inventory trajectory supporting its price target.
LNG Exports Add a Global Pull
An LNG terminal functions much like a massive industrial consumer. When a brand-new terminal comes online or an existing plant increases output, additional gas must be produced, pulled from storage reserves, or diverted away from other end users.
Export demand also ties regional pricing together. A frigid Asian winter can intensify competition for spot cargoes, while European buyers busy restocking storage may bid for that same flexible supply. Higher overseas prices can incentivize U.S. terminals to operate at maximum capacity, tightening the domestic balance even if local weather conditions are mild.
This intercontinental link has only deepened. According to the International Energy Agency’s Q1 2026 review, global LNG production expanded by nearly 7 percent—equivalent to 38 billion cubic metres—over the course of 2025, with roughly three-quarters of that growth occurring in the second half of the year. Benchmark price correlation between Europe and Asia ultimately hit 0.955, underscoring how intensely cargo competition binds the two markets.
Conversely, an export outage can reverse these dynamics. International supply tightens as fewer shipments depart, but the gas that would have fed the terminal remains trapped in the domestic system, causing international prices to climb while the nearby U.S. pricing hub drops. A single event can thus trigger two entirely opposite market reactions.
When the Signals Collide
The most difficult trading days occur when fundamental indicators point in conflicting directions. A colder temperature outlook might support prices, yet a milder-than-expected weekly storage report could cap the rally. While robust LNG feedgas demand looks fundamentally bullish, an approaching hurricane introduces the immediate threat of a terminal shutdown.
Timing explains many of these apparent market contradictions. Weather forecasts look forward, storage reports reflect the preceding week, and LNG pipeline flows can shift dynamically throughout the day. A trader who treats these metrics as if they cover identical timeframes risks drawing flawed conclusions.
For instance, heating demand might remain weak during an unseasonably warm autumn, allowing storage inventories to replenish rapidly. At the exact same time, a new export facility might begin the commissioning process and gradually increase its feedgas consumption. Prices could stay soft initially due to comfortable inventory levels, only to surge later as sustained export demand extends into the winter months.
Building a More Useful Forecast
A practical market outlook relies on scenario analysis rather than a single, unyielding target. A base case might assume normal weather conditions, storage inventories sitting near seasonal norms, and steady LNG operations. A tighter scenario could combine prolonged freezing weather with heavy export volumes, while a looser scenario might pair mild temperatures with an unexpected terminal outage.
Market participants should closely monitor shifting assumptions rather than focusing solely on a published price target. A revised temperature map, an unexpected storage release, or an altered terminal operational schedule often carries far more weight than a minor adjustment to production figures. Regional pipeline constraints also demand close attention, since a nationally balanced market can still harbor an expensive local shortage.
No natural gas price prediction remains static for long. Its ultimate value lies in identifying which specific catalyst could alter the market balance, how fast that change might materialize, and which geographic pricing hub would feel the impact first.
Conclusion
Seasonal consumption patterns, storage inventories, and LNG exports collectively bind domestic supply and foreign demand together, establishing a rhythm dictated largely by the weather. These forces drive the most dramatic price movements when two or three of them converge simultaneously. Mapping these variables onto a precise timeline transforms a simple directional guess into a testable, dynamic forecast that can support actual purchasing decisions.