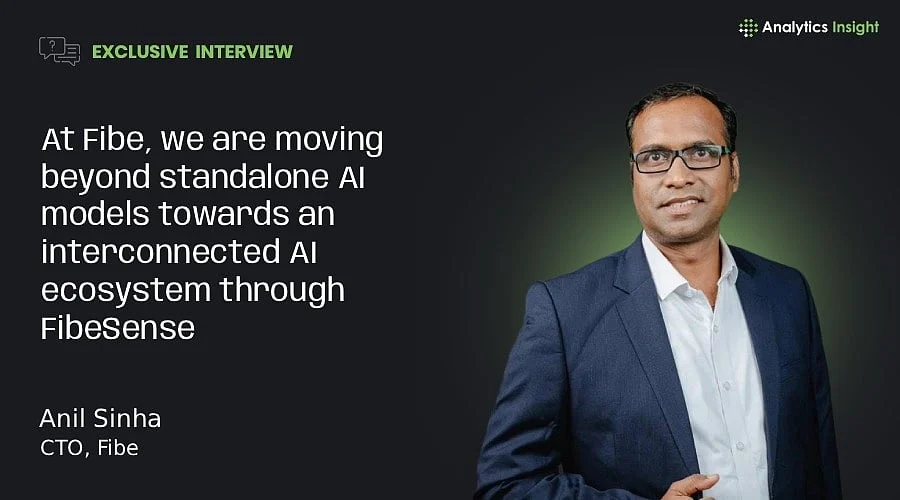
Fibe is transitioning beyond standalone AI models by introducing an interconnected AI ecosystem designed to enhance both underwriting and fraud detection. Through FibeSense, the company’s new AI platform, various capabilities are hosted on a shared intelligence foundation that allows insights generated by one agent to inform other decisions throughout the entire lending journey.
The updated architecture for fraud detection relies on seven specialised agents that operate in parallel via FibeSense. These agents evaluate identity duplication, KYC, bank statements, company validation, employment, geographic consistency, and—for returning customers—credit behaviour. A central orchestrator integrates their findings into a unified risk assessment, while Graph AI delivers a comprehensive view of the applicant’s surrounding network.
This automated framework accelerates decision-making times while preserving human oversight for flagged applications. Human reviewers are provided with combined intelligence derived from both the underwriting and fraud systems, supplying deeper context to evaluate potential anomalies.
Graph AI assists in uncovering hidden relationships and coordinated fraud rings that standard fraud detection and bureau-based underwriting might otherwise overlook. While an individual application can appear completely credible in isolation, its connections to other applications often tell a different story. Graph AI examines these relationships across Fibe’s entire customer base by analysing signals such as device IDs, IP addresses, GPS patterns, and banking transaction links.
For example, multiple applications carrying different identities might share a single device or feature linked banking activity—patterns that individual checks fail to capture. Surfacing these connections enables Fibe to spot potential fraud rings, mule networks, and coordinated actions earlier in the customer journey.
Although bureau information remains essential for tracking credit history, it lacks network context. Graph AI bridges this gap, treating shared signals as triggers for further investigation rather than direct proof of wrongdoing. These findings are evaluated alongside other FibeSense results, alongside human review for flagged files.
Fibe’s AI orchestration layer bridges specialised fraud checks with the AI Scorecard to formulate a consolidated assessment for each application. While the fraud systems review identity, banking, employment, and network signals, the scorecard measures creditworthiness using nearly 27,500 variables, which incorporates bureau data as just one input. Consolidating these outputs creates a holistic view of the applicant and exposes inconsistencies that individual models could miss.
Roughly 90% of applications achieve processing without any human intervention. Fibe draws the line at flagged cases—whether triggered by a potential fraud signal or a credit anomaly—which are then directed to a human reviewer equipped with the combined FibeSense findings. Automation handles information processing swiftly and consistently, whereas human judgement is maintained for applications requiring closer scrutiny.
Deploying AI across millions of real-time financial decision points introduces significant engineering and governance challenges, particularly concerning explainability, data security, model reliability, and regulatory compliance. Maintaining dependability across millions of decisions executed in seconds led Fibe to construct FibeSense as a centralised platform, ensuring platform-level controls extend to every operating agent.
Explainability is prioritised because lending decisions must remain transparent to customers, credit teams, and regulators alike, each requiring varying levels of detail. Within FibeSense, each agent’s findings are logged alongside the final decision, allowing outcomes to be traced rather than reconstructed post-facto.
Data security is embedded natively into FibeSense. Every model and agent functions within a strict data boundary to keep customer information inside Fibe’s controlled environment, regardless of the volume of signals utilised. Consent, data minimisation, encryption, and strict access controls are integrated directly into the pipeline in compliance with the DPDP Act.
Reliability requires ongoing oversight. Every model on FibeSense undergoes continuous monitoring against live performance metrics, while challenger scorecards run in parallel with production models to test for superior approaches. New models are promoted only after proving their effectiveness, supported by fallback rules that preserve consistency.
Regulatory compliance unifies these principles, with the Reserve Bank of India’s (RBI) digital lending directions and its FREE-AI framework establishing explicit accountability. Practically, this mandates audit trails for every decision, pre- and post-deployment bias testing, and human accountability for the policies executed by the agents.
As AI becomes deeply embedded within the core architecture of financial services, the role of the CTO is evolving from constructing technical infrastructure toward managing AI strategy, self-healing systems, governance, and long-term business transformation. When AI directly influences fraud prevention, underwriting, and customer experience, technology choices directly shape financial outcomes, necessitating closer coordination with product, analytics, and risk teams to guarantee that AI serves distinct business purposes reliably during growth phases.
FibeSense serves as both a shared intelligence foundation and an extension of AI into technology operations. Its self-healing layer monitors system health and resolves low-priority technical issues without requiring engineering intervention, allowing technical teams to concentrate on more complex challenges and enhancements.
Governance remains a core component of this responsibility, ensuring customer data and decision signals stay within Fibe’s internal environment while human review is preserved for flagged fraud and credit cases. Ultimately, progress is evaluated by the quality of decisions enabled by the technology, alongside its speed, security, and reliability.