September 30 marks the closing date for the European Commission’s consultation on EU crypto rules. Banking regulators are urging the Commission to evaluate fresh regulations for decentralized finance (DeFi) lending and borrowing. While the deadline governs the submission of feedback regarding potential adjustments, it does not put any new lending mandates into effect.
EBA Asks EU to Examine Access to DeFi Loans
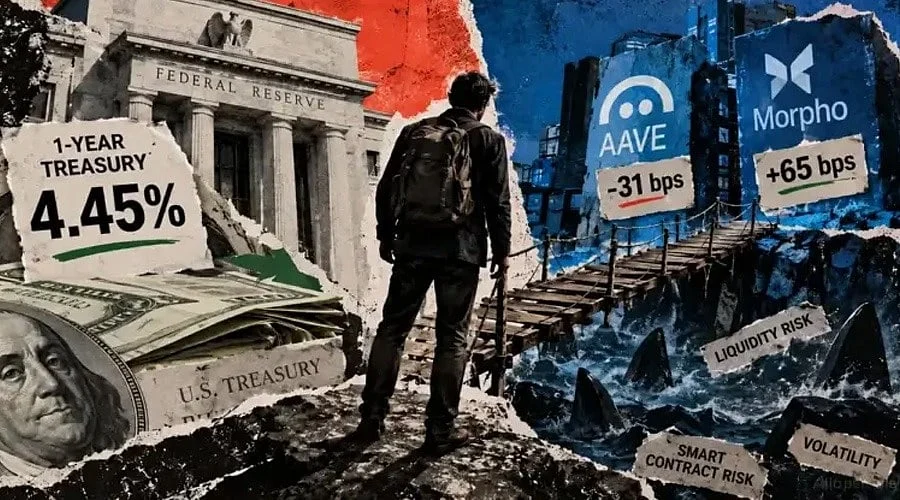
The European Banking Authority asked the Commission to evaluate regulations for entities that facilitate crypto loans. Published on September 24, the authority’s response additionally addresses cryptocurrency businesses that link users to DeFi lending via applications or software products. While an automated protocol may handle the loan execution, a commercial entity often manages the pathway users take to access it.
The EBA outlined two potential modifications to the Markets in Crypto-Assets Regulation (MiCA). The first option would incorporate crypto borrowing and lending into the official roster of regulated services, while the second would impose obligations on companies offering entry to DeFi lending. Before determining whether to put forward formal legislation, the Commission is required to analyze consumer risks, retail participation levels, and the overall scale of these operations.
Consumer Risks Drive Calls for Safeguards
The EBA suggested reviewing leverage restrictions, appropriateness assessments, and improved transparency regarding loan conditions. Furthermore, it recommended issuing cautions to clients interacting with protocols labeled as “truly decentralized.” An alternative proposal involves evaluating whether lending protocols could qualify for certifications verifying their resilience against cyberattacks.
According to the authority, critical information gaps persist concerning yields, fees, and sudden adjustments to collateral demands. It highlighted dangers associated with poor recordkeeping, system outages, cyber breaches, and losses driven by leverage. Furthermore, users might accumulate excessive debt when platforms fail to verify a borrower’s repayment capacity.
A distinct recommendation addresses loans utilizing specific stablecoins that lack an authorized issuer. The EBA indicated that MiCA could prohibit crypto firms from brokering or supporting loans that feature these tokens, with the recommendation targeting the service-providing enterprises. Ultimately, lawmakers would still need to determine how revised regulations would govern users who engage with smart contracts independently.
Central Banks Seek Wider Crypto Lending Rules
The European System of Central Banks has provided its own feedback regarding the MiCA review, advocating for EU oversight of crypto borrowing, lending, and staking. Additionally, central bankers are pushing for the current prohibition on stablecoin interest to encompass indirect yields distributed via connected platforms. These proposals necessitate additional legislative measures before taking effect as law.
These twin submissions present legislators with a distinct operational challenge. Because users can access lending protocols through direct smart contract interactions, alternative interfaces, or corporate applications, any prospective regulation must clearly establish which companies offer a regulated service and outline the specific obligations tied to each access channel.
The Commission’s targeted consultation is scheduled to conclude on September 30 at 11:59 p.m. Central European Summer Time. The collected comments will shape the forthcoming report on MiCA’s implementation, and the Commission has stated it may accompany that report with a legislative proposal should it determine that modifications are necessary.
Also Read: EU Regulators Put Quantum Risk on Crypto Custody & Bank Agenda